
How much hail damage to replace roof systems is the question I get asked almost weekly. And honestly? Most contractors won’t give you a straight answer. Here’s the deal. I’ve watched hundreds of homeowners get confused by vague estimates and pushy sales tactics after hail storms roll through their neighborhoods.
Let me break down exactly what you need to know.
The Size That Actually Matters
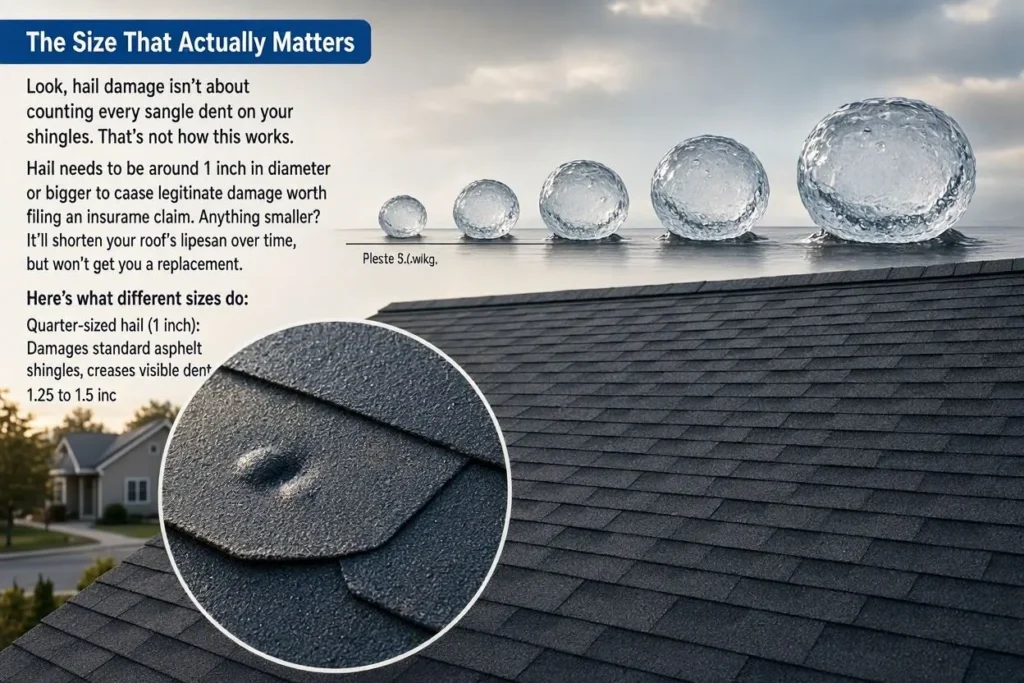
Look, hail damage isn’t about counting every single dent on your shingles. That’s not how this works. Hail needs to be around 1 inch in diameter or bigger to cause legitimate damage worth filing an insurance claim. Anything smaller? It’ll shorten your roof’s lifespan over time, but won’t get you a replacement.
Here’s what different sizes do:
- Quarter-sized hail (1 inch): Damages standard asphalt shingles, creates visible dents
- 1.25 to 1.5 inches: Guaranteed damage to most roofing materials
- 1.75 to 2 inches: Even impact-resistant shingles with Class 3 or Class 4 ratings get compromised
I saw a client last month with brand-new Owens Corning Duration shingles. The storm came through with 1.5-inch hail. The roof looked fine to him. But the trained eye? We found bruised shingles everywhere.
What Your Insurance Adjuster Actually Looks For
Your homeowners insurance company doesn’t care about your feelings. They care about facts. When the insurance adjuster shows up, they’re hunting for specific damage indicators. Not just shingle dents.
They check these spots:
- Roof vents for dings and spatter marks
- Soft metals and roof flashing
- Gutters and downspouts for visible impacts
- Any roof penetrations that show clear strikes
Here’s the kicker. Sometimes damage doesn’t show up immediately. Hail bruises shingles, then rain washes out the granule loss over 3-5 months.
One roofing contractor I know always tells clients to wait before filing. Smart move. More damage shows up later, stronger claims get approved.
The Insurance Policy Game Nobody Explains
This part makes me angry. Because most people have no clue what policy they’re actually paying for.
You’ve got two options:
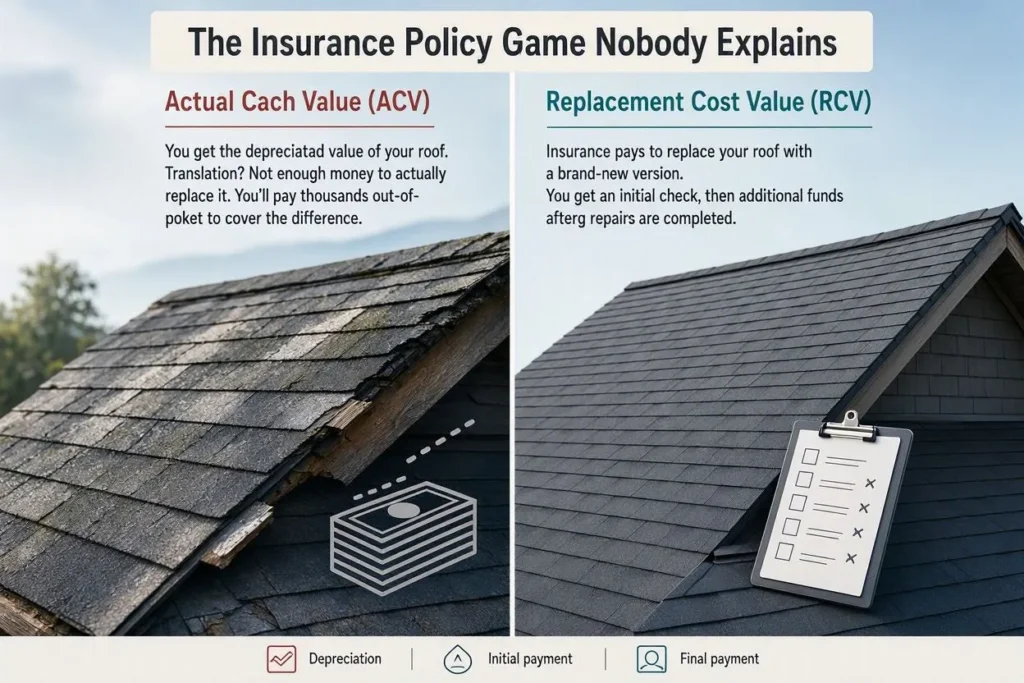
Actual Cash Value (ACV): You get the depreciated value of your roof. Translation? Not enough money to actually replace it. You’ll pay thousands out-of-pocket to cover the difference.
Replacement Cost Value (RCV): Insurance pays to replace your roof with a brand-new version. You get an initial check, then recoverable depreciation after the work is done with photo evidence.
I’ve seen homeowners with ACV policies think they’re covered. Then the check arrives. It’s half what they need. Brutal wake-up call.
How to Spot Hail Damage Without Climbing Up There
Don’t get on your roof. Seriously. Leave that to professional roofing contractors who know how to walk on shingles safely. But you can check for collateral damage from the ground. This tells you if filing a claim makes sense.
Walk around your property and look for:
- Dented downspouts (above 5 feet so it can’t be blamed on lawnmowers)
- Strikes on your garage door
- Holes in window screens
- Dings on painted wood or shutters
- Damage to your electric meter or AC unit
- Mailbox dents and soft metal damage
- Spatter marks on your grill
Found multiple signs? Your roof probably took a beating too. Check your gutters for loose granules. After a hail storm, granule loss is massive if damage occurred. You’ll see piles of it around downspouts.
The Timeline That Could Cost You Everything
Here’s where people mess up. You typically have one year from the storm date to file your insurance claim. “But how will they know when it happened?” Wrong question. Insurance companies access hail maps showing exactly when and where storms hit. They know. Trust me.
I watched a homeowner wait 14 months to file because they “weren’t sure.” Claim denied. Thousands of dollars lost. Don’t be that person.
File as soon as you confirm damage exists.
When Repair Makes More Sense Than Replacement
Not every hail storm means you need a full roof replacement. Real talk. If you’ve got a newer roof (under 5 years) with impact-resistant shingles, sometimes limited damage only needs repairs. But here’s the catch.
Piecemeal repairs can void your manufacturer warranty. That lifetime warranty on those architectural shingles? Gone if repairs aren’t done right.
I met a guy on Reddit who had a 3-month-old roof get hit with 1.5-inch hail. Two companies said full replacement was needed. His original roofer? Said wait and monitor it. Smart call. Sometimes damage isn’t as bad as storm-chasing contractors claim.
The Red Flags Nobody Warns You About
Storm chasers flood neighborhoods after hail damage. They knock on doors, pressure you to sign contracts, promise easy insurance money.
Watch for these warning signs:
- Pushy sales tactics demanding immediate decisions
- Companies with no local address or history
- Promises to “handle everything” with your insurance
- Offers to waive your deductible (that’s insurance fraud)
- No proper licensing or credentials
Find established roofing companies. Check their reputation. Get multiple inspections before deciding anything. Your insurance company might even recommend contractors. Use that list as a starting point.
What Actually Happens During the Claim Process
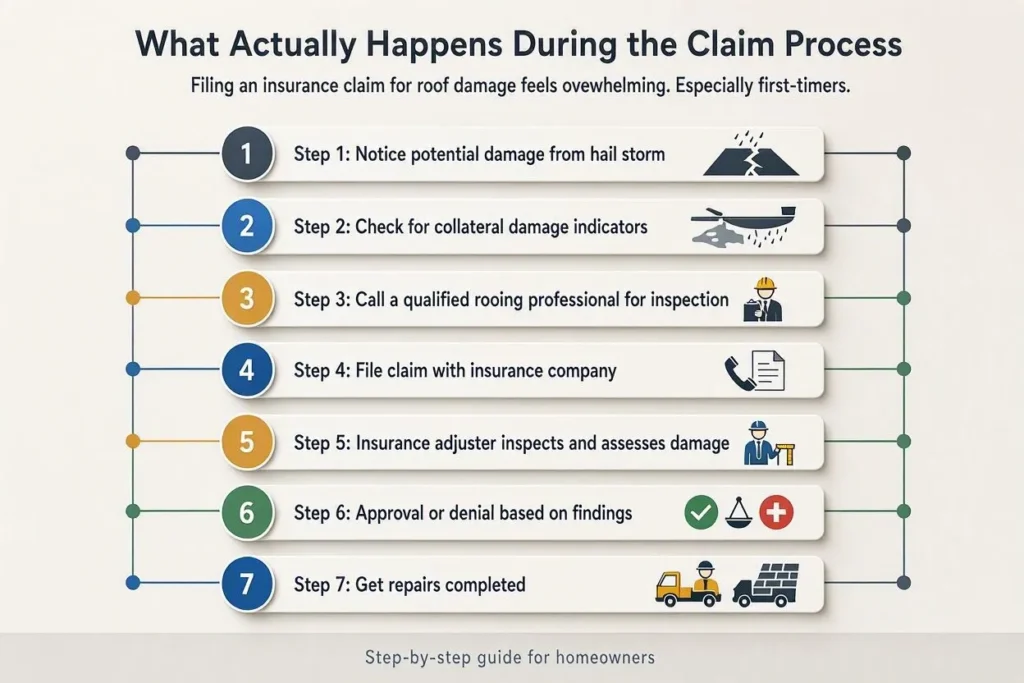
Filing an insurance claim for roof damage feels overwhelming. Especially first-timers.
Here’s the actual process:
- Step 1: Notice potential damage from hail storm
- Step 2: Check for collateral damage indicators
- Step 3: Call a qualified roofing professional for inspection
- Step 4: File claim with insurance company
- Step 5: Insurance adjuster inspects and assesses damage
- Step 6: Approval or denial based on findings
- Step 7: Get roof replacement or repairs completed
- Step 8: Submit photo evidence for final payment
The whole thing takes 2-6 weeks typically. Sometimes longer if supplemental claims are needed to maximize your payout. Work with roofing contractors experienced in insurance claims. They’ll supplement properly and fight for maximum coverage.
The Honest Cost-Benefit Analysis
Here’s what nobody tells you upfront. Filing a claim affects your insurance premiums. Not every hail storm warrants a claim. If damage is minimal and you’ve got a high deductible? Might not be worth it.
Consider these factors:
- Your deductible amount
- Extent of widespread damage across the roof
- Age and current condition of shingles
- Likelihood of future problems from compromised integrity
- Impact on insurance rates long-term
I’ve seen neighbors all file claims after one storm. Half didn’t actually need replacements. They just got talked into it by aggressive contractors. Be smarter than that.
Conclusion
At the end of the day, how much hail damage to replace roof systems comes down to professional assessment plus your specific situation. Get inspections from multiple sources. Let your insurance adjuster make the official call. Don’t trust any single contractor’s opinion without verification. Your roof protects everything underneath. Make decisions based on facts, not fear or pressure tactics.