No. A home warranty doesn’t pay for roof replacement, and many base plans leave the roof out entirely. What some providers do sell is roof leak coverage: an optional add-on (or a top-tier plan feature) that pays a roofing contractor to repair an active leak over the occupied living area, up to a per-claim cap. Storm damage goes to homeowners insurance, defective shingles go to the shingle manufacturer warranty, and a roof that simply ages out is the homeowner’s cost.
Key Takeaways
- A home warranty is a residential service contract. It repairs worn-out home systems and appliances, and roof coverage is usually an optional add-on or a top-tier plan feature.
- Roof leak coverage repairs the leak source, typically at the shingles, flashing, sealants, or underlayment, and only over the occupied living area. Garages, porches, and patios are usually out.
- No standard home warranty pays for a full roof replacement. Reported per-claim caps are often in the hundreds to low thousands of dollars, far below a reroofing bill.
- Hail, wind, hurricane, and falling-tree damage go to homeowners insurance, not the home warranty.
- Defective shingles fall under the manufacturer warranty, and installation errors fall under the roofing contractor’s workmanship warranty.
- Preexisting leaks, roofs that need replacement rather than repair, missing maintenance records, and excluded roof types are the most common reasons roof claims are denied.
Roof Repair vs. Replacement: Who Pays at a Glance
Most people searching “does home warranty cover roof” are really asking one question: what is wrong with my roof, and who pays for it? Start with the cause.
| Roof Situation | Likely Fix | Who Typically Pays |
|---|---|---|
| Slow leak from worn shingles, cracked flashing, or a failing sealant | Roof repair | Home warranty roof leak add-on, or the homeowner |
| Hail, wind, hurricane, or falling-tree damage | Repair or replacement | Homeowners insurance (after the deductible) |
| Shingles fail years ahead of schedule | Repair or replacement | Shingle manufacturer warranty |
| Leak traced to a bad installation | Repair or replacement | Roofing contractor’s workmanship warranty |
| Roof at the end of its service life | Full replacement (reroofing) | Homeowner |
The rest of this guide explains each row, then shows how to read the contract clauses that decide whether a claim pays.
What Is a Home Warranty?
A home warranty is a residential service contract that pays to repair or replace covered home systems and appliances when they fail from normal use. The roof is usually the exception. It sits outside the base contract, so homeowners only get roof protection through an optional add-on or a top-tier plan. A few providers, including America’s Preferred Home Warranty and Select Home Warranty, say they include roof leak repair in their standard plans, so the plan name matters less than the written contract.
A typical plan covers items such as the heating, ventilation, and air conditioning (HVAC) system, plumbing, electrical wiring, the water heater, and major kitchen appliances. Payment works in two layers: a premium (annual or monthly), then a service fee each time the provider sends a contractor.
States regulate these companies under a different legal name, “residential service contract.” In many states the insurance department handles licensing and oversight, so a consumer can check a provider’s standing and file a complaint in one place.
The four products that can pay for roof problems compare like this.
| Product | What It Covers | Who Issues It | Typical Trigger |
|---|---|---|---|
| Home warranty | Leak repair from normal use (add-on) | Home warranty company | Slow leak over living space |
| Homeowners insurance | Sudden, accidental damage | Insurance carrier | Hail, wind, fire, falling tree |
| Manufacturer warranty | Defects in roofing materials | Shingle manufacturer | Premature shingle failure |
| Workmanship warranty | Installation errors | Roofing contractor | Leak caused by faulty installation |
Does a Home Warranty Cover Roof Leaks?
Yes, but only when the contract includes roof leak coverage, usually as a paid add-on or a feature of the highest plan tier. That coverage fixes the leak itself over the occupied living area, up to a per-claim cap. It stops short of replacing the roof.
A base plan without the roof leak add-on pays nothing toward a roof leak. Confirm the coverage appears on the signed contract, not just on the sales page.
What Roof Leak Coverage Usually Repairs
Roof leak coverage pays a roofing contractor to find the source of an active leak and repair it. Provider contracts and consumer guides commonly list these repairable items:
- Shingle or shake repair and replacement at the leak point
- Flashing repair around chimneys, vents, valleys, and walls
- Cracked or failing roof sealants and seams
- Pipe and exhaust vent seals (vent boots)
- Underlayment repair
- Small punctures and popped-up nails
- Seam repairs on a flat or rolled roof, where the roof type is covered
Location matters most. The leak has to sit over the occupied living area, meaning the heated and cooled rooms where people live day to day. A leak over a bedroom qualifies under most add-ons, while one over a detached garage or porch does not.
Common Roof Leak Exclusions
| Exclusion | Why It Is Excluded |
|---|---|
| Garages, porches, patios, sheds, and decks | Outside the occupied living area |
| Preexisting leaks | Existed before coverage started |
| Hail, wind, hurricane, and tree damage | Covered by homeowners insurance instead |
| Tile, slate, metal, and flat roofs | Specialty materials often excluded |
| Gutters, downspouts, and skylights | Treated as separate exterior items |
| Structural roof damage and decking replacement | Beyond repair-only contract terms |
| Interior water damage and mold | Contracts repair the leak source only |
| Full roof replacement | Exceeds repair-only contract terms |
| Improper installation | Treated as a contractor warranty issue |
Does a home warranty cover a roof that already leaked before the contract started? No. Contracts exclude preexisting conditions, and a home inspection report that mentions roof stains or soft decking can serve as evidence that the problem was already there.
Coverage Caps, Service Fees, and Add-On Cost
The per-claim cap is the most the provider will pay for one roof leak repair. Some contracts also set an annual cap across the contract term. Published figures vary by provider, plan, and state, so treat the ranges below as ballparks and confirm them in the sample contract:
- Roof leak caps are often reported between roughly $400 and $1,500. American Home Shield’s ShieldPlatinum plan, for example, has been reported to pay up to $1,000 per plan term for roof leak repair.
- Service fees commonly run about $75 to $125 per visit, and they’re owed even when the claim is later denied.
- Roof leak add-ons are often priced at roughly $8 a month where sold separately, though prices vary.
- A typical leak repair can run a few hundred dollars, and more for tile or metal roofs.
When a roofer’s repair estimate exceeds the cap, the homeowner pays the difference. Some providers will apply the cap toward a replacement, but the homeowner still funds the rest of the job.
Does a Home Warranty Cover Roof Replacement?
No. A home warranty does not cover a full roof replacement, even with roof leak coverage. This is the one place roofs differ from other covered systems: if an HVAC unit can’t be repaired, many contracts replace it, but roof benefits stop at repairing specific leaks.
Anyone asking “does home warranty cover roof replacement” gets the same answer from every standard contract. Once the provider’s contractor decides the roof can’t be repaired, the claim typically ends there.
Scale is the reason. Roofers price replacement by the roofing square, which equals 100 square feet (9.29 square meters) of roof surface. A full reroof means tear-off, disposal, new underlayment, flashing, and shingles across many squares. One consumer-finance guide puts the average replacement at around $9,000, and more for complex roofs or premium materials. That is far above any repair-only cap.
What Pays for a Full Roof Replacement Instead
- Homeowners insurance pays when a covered peril, such as hail or wind, damages the roof beyond repair.
- The shingle manufacturer warranty pays when a confirmed material defect causes early failure, under the warranty’s terms.
- The workmanship warranty pays when the installing contractor’s errors cause the failure within the warranty term.
- The homeowner pays when the roof reaches the end of its service life from age alone.
Roof Leak Repair or Full Replacement? How to Decide
This is where most roof questions are actually settled, and where a roofing contractor’s inspection earns its fee. Warning signs that a roof is moving from repairable to replaceable:
- Widespread granule loss, curling, cracking, or missing shingles across several slopes
- Repeated leaks in different places, not one failed flashing detail
- Soft or sagging roof decking, or water stains spreading across ceilings
- A roof at or beyond the typical lifespan for its material
Rough lifespan ranges, which vary by climate, ventilation, and installation quality:
| Roof Material | Approximate Service Life |
|---|---|
| Asphalt shingles | About 15 to 30 years |
| Wood shake | About 20 to 30 years |
| Metal | About 40 to 70 years |
| Clay or concrete tile | About 50 years or more |
| Slate | 75 years or more |
A single localized leak on a mid-life asphalt shingle roof is a good candidate for repair, and that is exactly where a roof leak add-on pays off. An old roof with failure across the whole surface is a replacement, which no home warranty funds. Ask the roofer for a written estimate for both options so you can compare repair costs against replacement costs before deciding.
What Roof Parts Does a Home Warranty Cover?
A home warranty with roof coverage repairs the shingles and flashing at the leak location over the occupied living area. Other parts usually sit outside coverage: gutters, downspouts, skylights, solar panels, and roof-mounted equipment, and many contracts also exclude tile, slate, metal, and flat roofs.
Flashing is the thin metal or membrane that seals joints around chimneys, vents, valleys, and walls. Failed flashing is behind many roof leaks, so look for flashing named as a covered component, not just implied.
| Roof Part | Usually Covered | Notes |
|---|---|---|
| Shingles at leak point | Yes, with add-on | Over occupied living area only |
| Flashing at leak point | Often | Confirm it is named in the contract |
| Sealants and vent boots | Often | Check the component list |
| Underlayment | Sometimes | Repair at the leak point only |
| Roof decking | Rarely | Structural repair usually excluded |
| Gutters and downspouts | No | Treated as exterior maintenance |
| Skylights | Often excluded | Check the exclusion list |
| Chimneys | Often excluded | Masonry repair rarely included |
| Solar panels | No | Removal and reinstall not covered |
| Roof over garage or porch | No | Outside occupied living area |
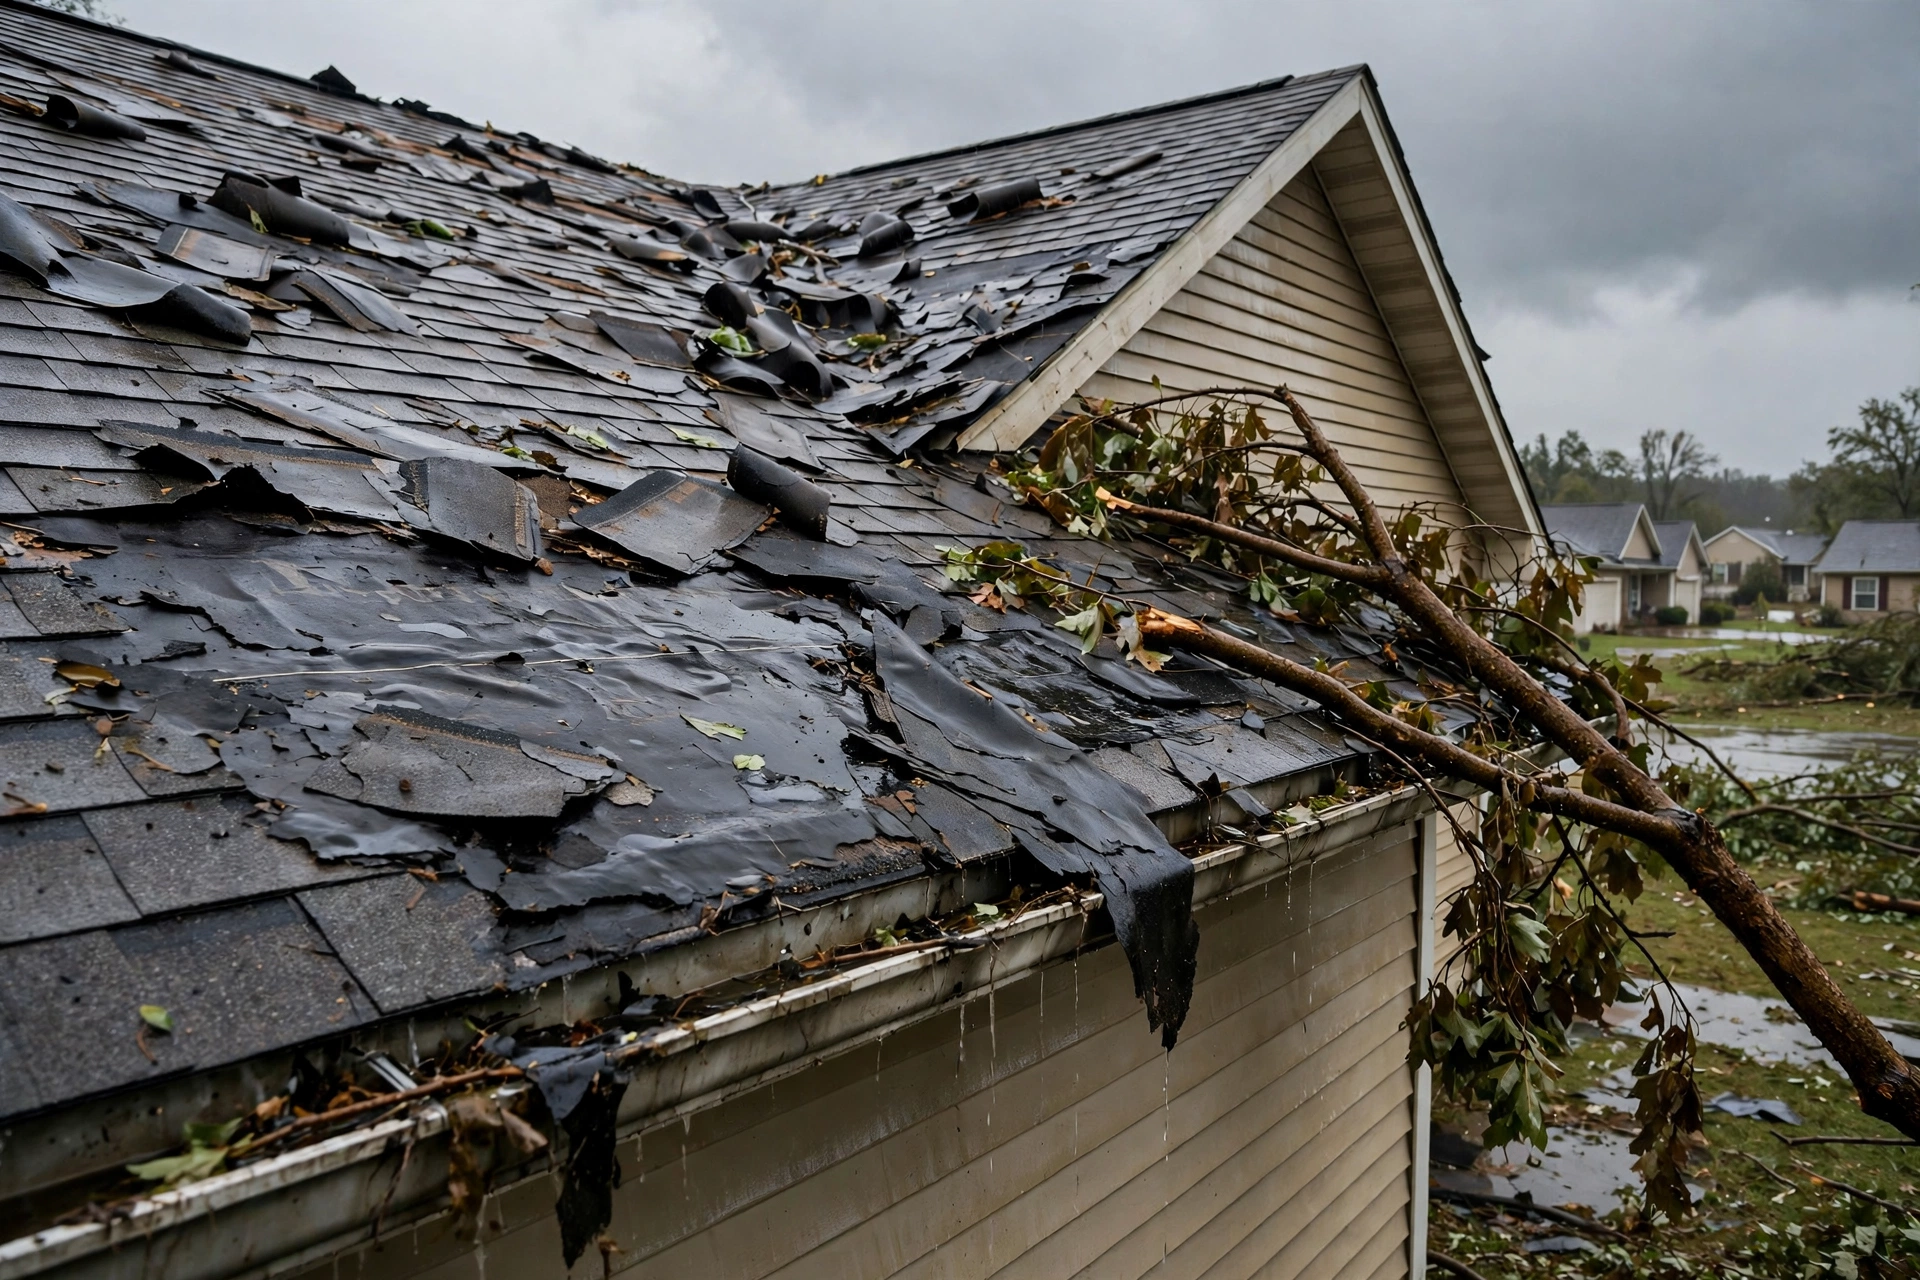
Does a Home Warranty Cover Roof Damage from Storms?
No. A home warranty does not cover roof damage from hail, wind, hurricanes, or falling trees. Those are sudden, accidental perils under a homeowners insurance policy, so the homeowner files with the insurance carrier and pays the deductible before the insurer covers repairs.
Many policies in hail-prone states, Texas and Colorado among them, carry a separate wind and hail deductible, and Oklahoma policies often do as well. Coastal states such as Florida often use a separate hurricane deductible. Check the declarations page.
The National Weather Service classifies hail 1 inch (2.5 centimeters) in diameter or larger as severe. Stones that size can crack or dent asphalt shingles and strip their granules, so schedule a roof inspection after any severe hail event.
Flooding is its own case. A standard homeowners policy excludes flood, which requires a separate policy, such as one through the National Flood Insurance Program (NFIP).
How to File a Hail Claim with Insurance
- Photograph the roof, gutters, siding, and vehicles from the ground on the day of the storm.
- Record the storm date and time using local weather reports.
- Call the insurance carrier or open a claim online promptly, following the policy’s reporting deadline.
- Schedule an inspection with a licensed local roofer for an independent damage estimate.
- Meet the insurance adjuster on site and share the roofer’s findings.
- Review the settlement against the policy’s wind and hail deductible before approving repairs.
Who Pays for Each Type of Roof Damage?
The cause of damage decides who pays: a home warranty with leak coverage pays for wear-related leaks, homeowners insurance pays for sudden storm and accident damage, the manufacturer pays for defective materials, and the contractor pays for installation errors. Roof age and neglect shift the cost back to the homeowner.
| Roof Problem | Typical Payer | Key Condition |
|---|---|---|
| Slow leak from aging shingles | Home warranty add-on | Over living area, not preexisting |
| Hail damage | Homeowners insurance | Wind and hail deductible applies |
| Wind-lifted or missing shingles | Homeowners insurance | Sudden event with documented date |
| Tree falls on roof | Homeowners insurance | Covered peril under the policy |
| Shingles fail early | Manufacturer warranty | Registered warranty, confirmed defect |
| Leak from bad installation | Workmanship warranty | Within the contractor’s warranty term |
| Roof at end of life | Homeowner | No product pays for age alone |
How Is a Roof Warranty Different from a Home Warranty?
A roof warranty covers the roof itself, either the materials through the shingle manufacturer or the labor through the installing roofing contractor. A home warranty is a service contract covering many home systems. Roof warranties attach to a specific installation, while home warranties renew yearly with any provider.
GAF, Owens Corning, and CertainTeed issue material warranties on their roofing products. Many also offer enhanced warranties when a certified contractor installs a complete roof system, and some enhanced tiers add workmanship protection.
| Feature | Home Warranty | Manufacturer Warranty | Workmanship Warranty |
|---|---|---|---|
| Covers | Leak repair (add-on) | Material defects | Installation errors |
| Issued By | Warranty company | Shingle manufacturer | Roofing contractor |
| Term | One year, renewable | Varies by product tier | Varies by contractor |
| Transferable | Often, per contract | Often, with registration | Varies by contractor |
| Cost | Premium plus service fee | Included; enhanced tiers extra | Included in install price |
Manufacturer shingle warranties often run for decades, which is why “30-year roof” is such a common phrase. Longer isn’t broader, though. The warranty pays for defects in the shingles themselves and, in some tiers, installation errors, not for the normal aging that wears every roof down.
Does Homeowners Insurance Cover a Roof Leak?
Yes, when a sudden, accidental event such as hail, wind, or a falling tree causes it. A standard Homeowners 3 Special Form (HO-3) policy excludes leaks from age, wear and tear, or neglected maintenance, leaving those to a home warranty add-on or the homeowner.
The HO-3 is the most common homeowners policy form in the US. It covers the dwelling against all perils except those named in its exclusions section, and wear and tear is named there. Insurance may also pay for interior water damage when a covered peril caused the leak, while a home warranty fixes only the leak source.
How Roof Age Changes the Insurance Payout
With a replacement cost value (RCV) policy, the insurer pays to replace damaged roofing with new material, minus the deductible. An actual cash value (ACV) policy subtracts depreciation for the roof’s age before paying. Some insurers settle older roofs on an ACV basis or apply a roof payment schedule that shrinks payouts as the roof ages.
Check the roof settlement terms on the declarations page or in a roof endorsement. Each carrier sets its own age thresholds, so ask the agent directly.
Which Home Warranty Companies Cover Roofs?
Several US providers advertise roof leak coverage, including American Home Shield, Choice Home Warranty, Liberty Home Guard, Select Home Warranty, America’s Preferred Home Warranty, and 2-10 Home Buyers Warranty. Terms change by plan, state, and contract year, so the current sample contract is the only reliable source. Read each one for the cap, the covered roof types, and any living-area limit.
Do home warranties cover roofs the same way across providers? No. Roof leak availability and plan-tier placement differ between companies and between states, and so do dollar caps.
| Provider | What to Verify | Where to Look |
|---|---|---|
| American Home Shield | Plan tier with roof leak terms, cap | Sample contract on ahs.com |
| Choice Home Warranty | Roof leak add-on availability and cap | Sample contract on provider site |
| Liberty Home Guard | Roof leak add-on terms and cap | Plan details and sample contract |
| Select Home Warranty | Roof leak terms by plan, service fee | Plan details and sample contract |
| Any provider | State-specific terms and licensing | State insurance department or regulator |
Which Roof Types Providers Exclude
Roof leak add-ons are commonly written for shingle, shake, and composition roofs. Many contracts exclude flat roofs, tile, slate, metal, and other specialty materials, and some cover only certain ones. A home with a shingle main roof and a flat-roof addition may get coverage on one section and none on the other. Confirm each section’s material against the exclusion list.
Contract Clauses That Decide Home Warranty Roof Coverage
Five clauses decide whether a roof claim pays: the occupied living area limit, the per-claim cap, the preexisting condition exclusion, the maintenance requirement, and the roof type exclusion. The waiting period and service fee also matter. Find each one in the sample contract before paying.
| Clause | What It Says | What to Check |
|---|---|---|
| Occupied living area | Covers leaks over lived-in rooms | Status of garages, porches, additions |
| Per-claim cap | Maximum paid per leak | Dollar limit versus local repair costs |
| Preexisting condition | Excludes problems before coverage | How the provider proves prior damage |
| Maintenance requirement | Requires reasonable upkeep | Records the provider may request |
| Roof type exclusion | Lists excluded materials | Each roof section’s material |
| Waiting period | Delays coverage after purchase | Start date for roof claims |
| Service fee | Charge per contractor visit | Fee owed on denied claims |
Why Do Home Warranty Roof Claims Get Denied?
Claims are usually denied because the leak existed before coverage started, the roof needs replacement rather than repair, required maintenance was skipped, the leak sits outside the occupied living area, or the damage came from a storm or bad installation. Homeowners insurance handles sudden weather events, not the warranty company.
Will a home warranty cover roof leaks on an old roof? Only if the roof is still repairable and the leak is new. A roof at the end of its service life gets classified as needing replacement, which the contract excludes. And a homeowner who never bought the roof leak add-on has no roof coverage to claim against.
How to Appeal a Denied Roof Claim
- Request the denial in writing with the specific contract clause cited.
- Hire an independent licensed roofer to inspect the roof and document the leak’s cause and age.
- Gather maintenance records, repair receipts, inspection reports, and dated photos.
- Submit a written appeal that answers the cited clause point by point.
- File a complaint with the state insurance department or the agency that regulates residential service contracts in your state.
- Post a factual complaint with the Better Business Bureau (BBB) if the provider does not respond.
Is a Roof Leak Add-On Worth the Cost?
It’s worth buying when the roof is mid-life, made of asphalt shingles, and sits mostly over occupied living space. A useful side benefit: a covered repair makes you more likely to call a roofer at the first sign of a leak, when leaks are cheapest to fix. The add-on loses value on a new roof already protected by warranties and on an old roof that needs replacement.
| Roof Situation | Add-On Value | Reason |
|---|---|---|
| New roof under warranty | Low | Manufacturer and workmanship warranties apply |
| Mid-life asphalt shingle roof | High | Repairable wear leaks are likely |
| Roof near end of life | Low | Claims likely classified as replacement |
| Tile, slate, metal, or flat roof | Low | Often an excluded roof type |
| Large garage or porch roof areas | Lower | Areas fall outside living space |
Ask a local roofer to estimate the roof’s remaining life, then compare the add-on price and cap against what a typical local repair costs.
How to Keep a Roof Leak Claim-Ready
Maintenance is both a contract requirement and the cheapest way to avoid a claim.
- Have a roofer inspect the roof once a year and after severe weather.
- Keep gutters and valleys clear so water doesn’t back up under shingles.
- Trim branches that overhang the roof.
- Replace cracked flashing and vent boots promptly.
- Keep dated photos, inspection reports, and repair receipts in one folder. They help prove the leak is new and the roof was maintained.
Roof Coverage When Buying or Selling a Home
During a sale, the seller often pays for a one-year home warranty for the buyer, the inspection report records the roof’s condition, and the existing roof warranty may transfer to the new owner. Buyers should review all three before closing.
A seller-paid home warranty rarely includes roof leak coverage unless the buyer asks for the add-on during negotiations. The inspection report cuts both ways: any roof problem listed there can be treated as preexisting, which blocks a later claim.
- Order a roof inspection from a licensed roofer in addition to the general home inspection.
- Ask the seller for the roof installation date, receipts, and any manufacturer or workmanship warranty documents.
- Negotiate repairs or a credit for any roof defects in the inspection report before closing.
- Request that the seller-paid home warranty include the roof leak add-on.
- Register the roof warranty transfer with the manufacturer after closing.
- Store all roof documents with the closing paperwork for future claims.
Can a Roof Warranty Transfer to a New Owner?
Yes, many shingle manufacturer warranties transfer when the transfer is registered within the manufacturer’s deadline. Some charge a transfer fee, limit the number of transfers, or reduce coverage after a change of ownership. The transfer usually requires the manufacturer’s form, proof of the original installation, the property address, and the closing date. Workmanship coverage depends on the contractor’s written terms, so contact the original installer directly.
How to File a Home Warranty Roof Leak Claim
File as soon as water appears, through the provider’s portal or phone line, and pay the service fee when the contractor arrives. Fast reporting limits interior damage and keeps the provider from blaming the delay for a larger repair.
- Contain the water with buckets and towels, and move belongings away from the leak.
- Stay off a wet or steep roof, since falls cause serious injuries.
- Photograph the ceiling stain, dripping water, and any visible roof damage from the ground.
- Confirm the contract includes roof leak coverage and that the leak sits over living space.
- File the claim through the provider’s portal or phone line before hiring any outside roofer.
- Meet the assigned contractor and point out every leak location.
- Keep the work order, invoice, and photos in one file.
Frequently Asked Questions
Is There a Home Warranty That Covers Roof Replacement?
No. Home warranty contracts limit roof benefits to leak repair up to a per-claim cap. Replacement money comes from homeowners insurance after a covered storm, from a manufacturer defect claim, or from the homeowner.
Does a Home Warranty Cover Gutters and Skylights?
In most contracts, no. Gutters and downspouts count as exterior maintenance, and skylights often appear on exclusion lists. Component lists differ by provider, so read the roof add-on language line by line.
How Much Does Roof Leak Coverage Cost?
It varies by provider, plan, and state. Add-ons are often reported at roughly $8 a month where sold separately, with per-claim caps in the hundreds to low thousands of dollars and service fees around $75 to $125. Get a written quote with the sample contract.
Will a Home Warranty Pay for Ceiling Damage from a Roof Leak?
No. Roof leak add-ons fix the leak source, not stained drywall, flooring, or mold. Homeowners insurance may pay for interior damage when a covered peril caused the leak.
Do Home Warranties Cover Roofs on Newly Built Homes?
The builder’s warranty usually applies first, and the shingle manufacturer warranty sits on top of it. A separate roof add-on adds little in those early years.
Does a Home Warranty Cover Mold from a Roof Leak?
Generally no. Mold is treated as secondary damage, and coverage depends heavily on the cause. Check the contract’s mold terms and ask your insurer about the interior damage.
Conclusion
The answer to “does home warranty cover roof” depends on the cause of the damage and the contract wording, not the plan’s marketing name. A roof leak add-on handles repairable leaks over living space. Storms go to insurance, while defects and bad installations belong to roof warranties.
The next step is practical, and it starts on the roof. Schedule a roof inspection with a licensed roofing contractor, who can check the shingles, flashing, and roof decking and give you a written estimate for roof repair versus full roof replacement. Leaks from worn asphalt shingles or failed flashing are usually repairable, while an aging roof near the end of its service life often needs reroofing. Once the roof is sound, register any transferable shingle warranty and keep the installation records. Then start a roof replacement fund sized to your roofer’s estimate, because a roof that simply wears out is the homeowner’s cost.