The right way to pay for a roof comes down to three things: how much equity you have in the house, your credit score, and how fast the repair needs to happen. If you’ve got solid equity and no urgent deadline, a home equity loan or HELOC will save you the most money over time, since both carry lower rates than unsecured borrowing. Need the cash in a day or two, or don’t have much equity to draw on? A personal loan or contractor financing will get you approved much faster.
This guide walks through nine ways to finance a roof replacement or repair in 2026, plus two options, PACE financing and energy-efficient mortgages, that most comparison articles never mention.
What’s the Best Roof Financing Option for You?
If you have at least 15 to 20 percent equity in your home and aren’t in a rush, a home equity loan or HELOC will get you the lowest rate. Need funding within a week? A personal loan is built for that. And if your equity is thin or your credit score sits under 620, government-backed options like FHA loans or financing offered directly through the roofing contractor tend to be easier to qualify for.
Speed, cost, and collateral risk pull against each other on every option in this list. Faster funding usually means a higher rate. Lower rates usually mean a longer wait and a lien on your house.
9 Roof Financing Options Compared
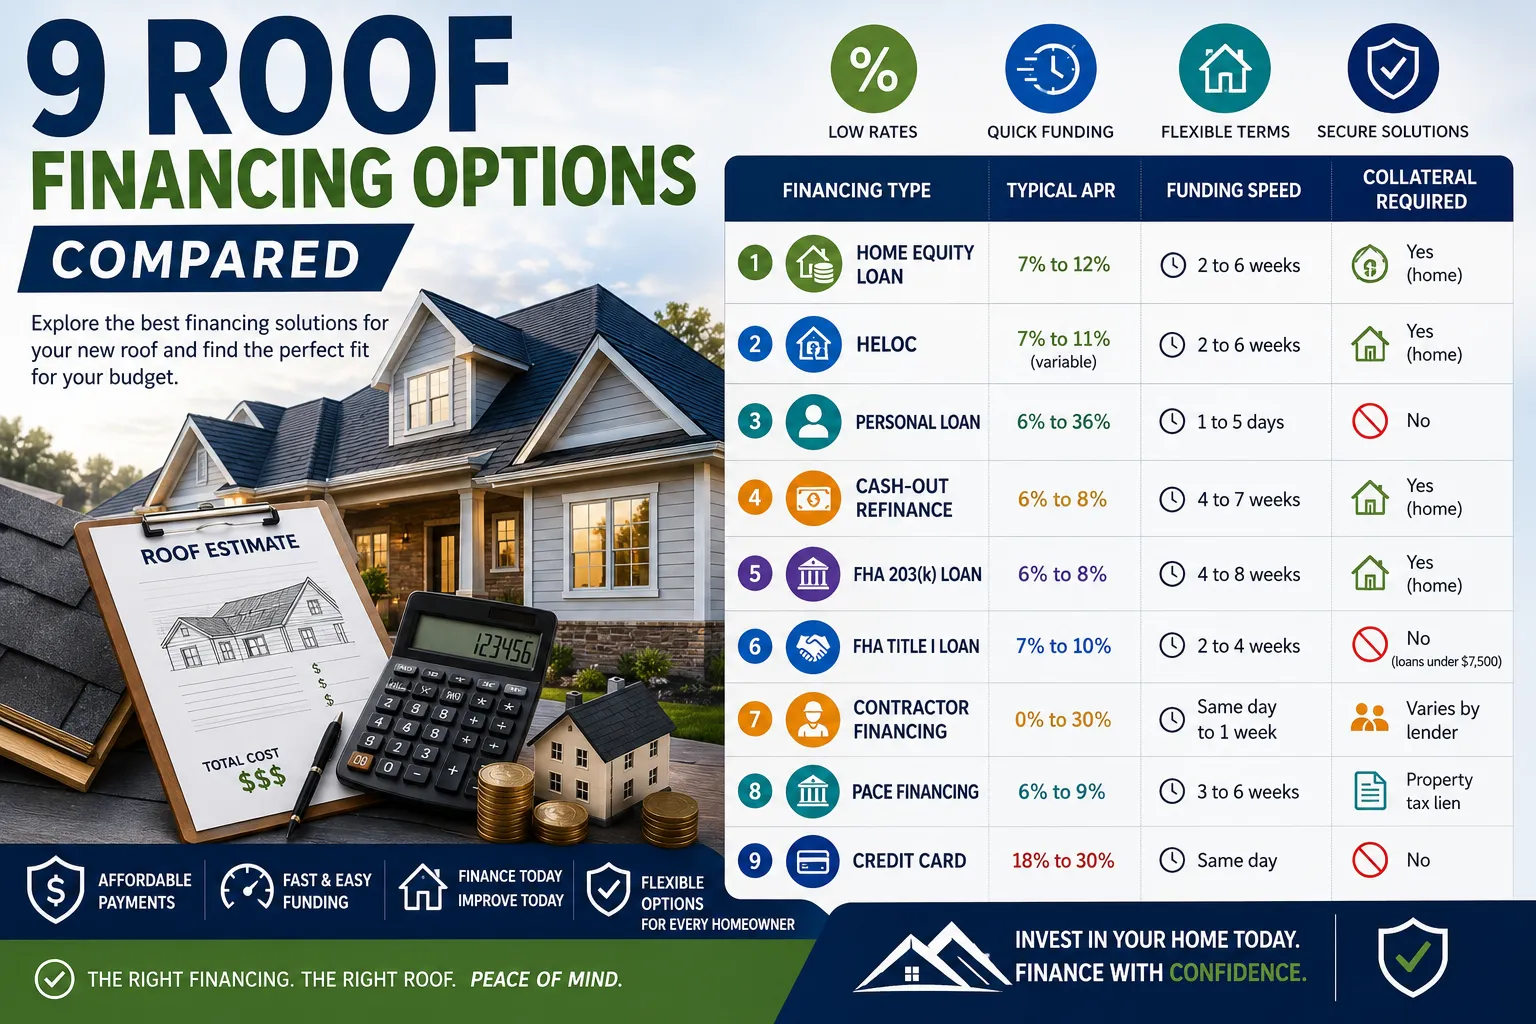
| Financing Type | Typical APR | Funding Speed | Collateral Required |
| Home equity loan | 7% to 12% | 2 to 6 weeks | Yes (home) |
| HELOC | 7% to 11% (variable) | 2 to 6 weeks | Yes (home) |
| Personal loan | 6% to 36% | 1 to 5 days | No |
| Cash-out refinance | 6% to 8% | 4 to 7 weeks | Yes (home) |
| FHA 203(k) loan | 6% to 8% | 4 to 8 weeks | Yes (home) |
| FHA Title I loan | 7% to 10% | 2 to 4 weeks | No (loans under $7,500) |
| Contractor financing | 0% to 30% | Same day to 1 week | Varies by lender |
| PACE financing | 6% to 9% | 3 to 6 weeks | Property tax lien |
| Credit card | 18% to 30% | Same day | No |
1. Home Equity Loan
You get a lump sum at a fixed rate and pay it back in equal installments over 5 to 30 years. Most lenders will let you borrow up to 80 to 90 percent of your home’s value, minus whatever you still owe on the mortgage. A 620 credit score clears the bar for most programs, but anything above 700 gets you the better rates. One thing worth knowing: interest on a home equity loan used for roof repairs is often tax-deductible, though you’ll want to confirm the current rule with a tax professional before you file.
2. HELOC (Home Equity Line of Credit)
Think of a HELOC as a credit card backed by your house. Instead of one lump sum, you draw funds as you need them, usually over a 10-year draw period, followed by 15 to 20 years of repayment. Rates are typically variable, so your payment can move up or down with the market. If you suspect the roof won’t be your only home improvement project this year, the flexibility here is real, since unused credit just sits available without a new application.
3. Personal Loan
This one’s unsecured, meaning nothing backs it but your signature, and lenders will approve anywhere from $1,000 to $100,000 within a few business days. Default on it and your house isn’t at risk. Rates run 6 to 36 percent APR, with the lowest numbers going to borrowers with a 690 credit score or higher. Terms max out around seven years, shorter than any equity-based option here.
4. Cash-Out Refinance
You replace your existing mortgage with a bigger one and pocket the difference. This makes the most sense when today’s mortgage rates are lower than what you’re currently paying, since you’d be lowering your overall payment while also funding the roof. Expect closing costs of 2 to 5 percent of the loan amount, and budget four to seven weeks for the appraisal and paperwork.
5. FHA 203(k) Loan (Federal Housing Administration)
An FHA 203(k) rolls the cost of the roof into your mortgage, based on what the home will be worth after the repair rather than what it’s worth today. Credit requirements are forgiving: as low as 500 with 10 percent equity, or 580 with 3.5 percent. That opens the door for borrowers who wouldn’t qualify conventionally. If the project runs over $75,000, though, you’ll need an FHA-approved consultant overseeing the work.
6. FHA Title I Loan
Title I loans fund home improvements, roofs included, without putting the house up as collateral, but only for loans under $7,500. Borrow more than that and you’ll need a mortgage or deed of trust on the property after all. This is a good fit for a smaller repair when you don’t have enough equity built up for a home equity loan or HELOC.
7. Roofing Contractor Financing
A lot of roofing companies partner with third-party lenders and can approve financing the same day you sign the contract. Strong credit sometimes gets you a 0 percent promotional rate for 12 to 24 months. Miss the payoff deadline, though, and many lenders charge retroactive interest on the entire original balance, not just what’s left. It’s also worth shopping the total project cost against other roofers first, since some contractors tack on a 10 percent “dealer fee” to cover the cost of offering interest-free financing.
8. PACE Financing (Property Assessed Clean Energy)
PACE lets you repay roof financing as a line item on your property tax bill instead of a separate loan payment. It only applies to energy-efficient upgrades, think reflective or cool-roof materials that cut cooling costs. Many PACE programs skip the credit check entirely, since approval leans on home equity and property tax history instead. The catch: the lien is attached to the property, not you, so if you sell before it’s paid off, the new owner inherits the balance.
9. Credit Card
Fine for repairs under $5,000, especially with a 0 percent introductory offer. Standard rates run 18 to 30 percent, which makes this the most expensive option on the list once that intro period ends. Use it if you can pay the balance off within 12 to 18 months, or if you need same-day funding and speed matters more than cost.
State and Local Programs Most Guides Skip
Two options rarely make it into roof financing articles: an Energy Efficient Mortgage (EEM) and state-level weatherization assistance.
An EEM, backed by the FHA or the VA, lets you finance energy-improving renovations as part of your mortgage. The loan amount is based on projected energy savings rather than just the home’s appraised value, and reflective shingles or added insulation typically qualify.
State and local weatherization programs offer grants or low-interest loans to income-qualified homeowners for repairs that cut energy use, including roof insulation and reflective roofing. Eligibility and funding vary a lot by state, so check with your state energy office before you look anywhere else.
How Much Does a New Roof Cost in 2026?
The average roof replacement runs $9,500, with most jobs falling between $5,900 and $13,200 depending on materials and size. Go premium (slate, metal, natural stone) and you’re looking at $32,000 or more. A few things drive that number:
- Roof size: $4 to $11 per square foot
- Roof pitch: an extra $1,000 to $3,000 in labor for steep roofs that need added safety equipment
- Materials: $5,800 to $20,000 for standard asphalt, more for metal or slate
- Labor: $40 to $90 per hour, roughly 60 percent of the total cost
- Permits: $100 to $1,400 depending on the municipality
- Inspections: $240 on average, required in some areas during the repair
How to Qualify for Roof Financing
Lenders check three numbers before approving anything: credit score, debt-to-income ratio (DTI), and, for equity products, loan-to-value ratio (LTV). DTI compares your monthly debt payments to your gross monthly income, and most lenders cap it at 43 to 50 percent. LTV compares the loan amount to your home’s appraised value, usually capped at 80 to 90 percent combined.
Four steps that actually move the needle:
- Get written estimates from three to five contractors so you know the real number you need
- Calculate your DTI yourself before a lender does, so there are no surprises
- Get prequalified with a few lenders. It won’t touch your credit score
- Pull together pay stubs, W-2s, and bank statements before you submit a formal application
Is Roof Replacement Covered by Homeowners Insurance?
Usually, yes, but only when the damage comes from a covered event like a storm, fire, or falling tree. Standard policies exclude damage from age or normal wear. And if your roof is older than 15 to 20 years, many insurers apply an actual cash value clause that factors in depreciation, so you get less than the full replacement cost. File the claim first, before you start shopping financing, since insurance proceeds can shrink or eliminate what you need to borrow.
Home Warranty vs. Homeowners Insurance for Roof Repairs
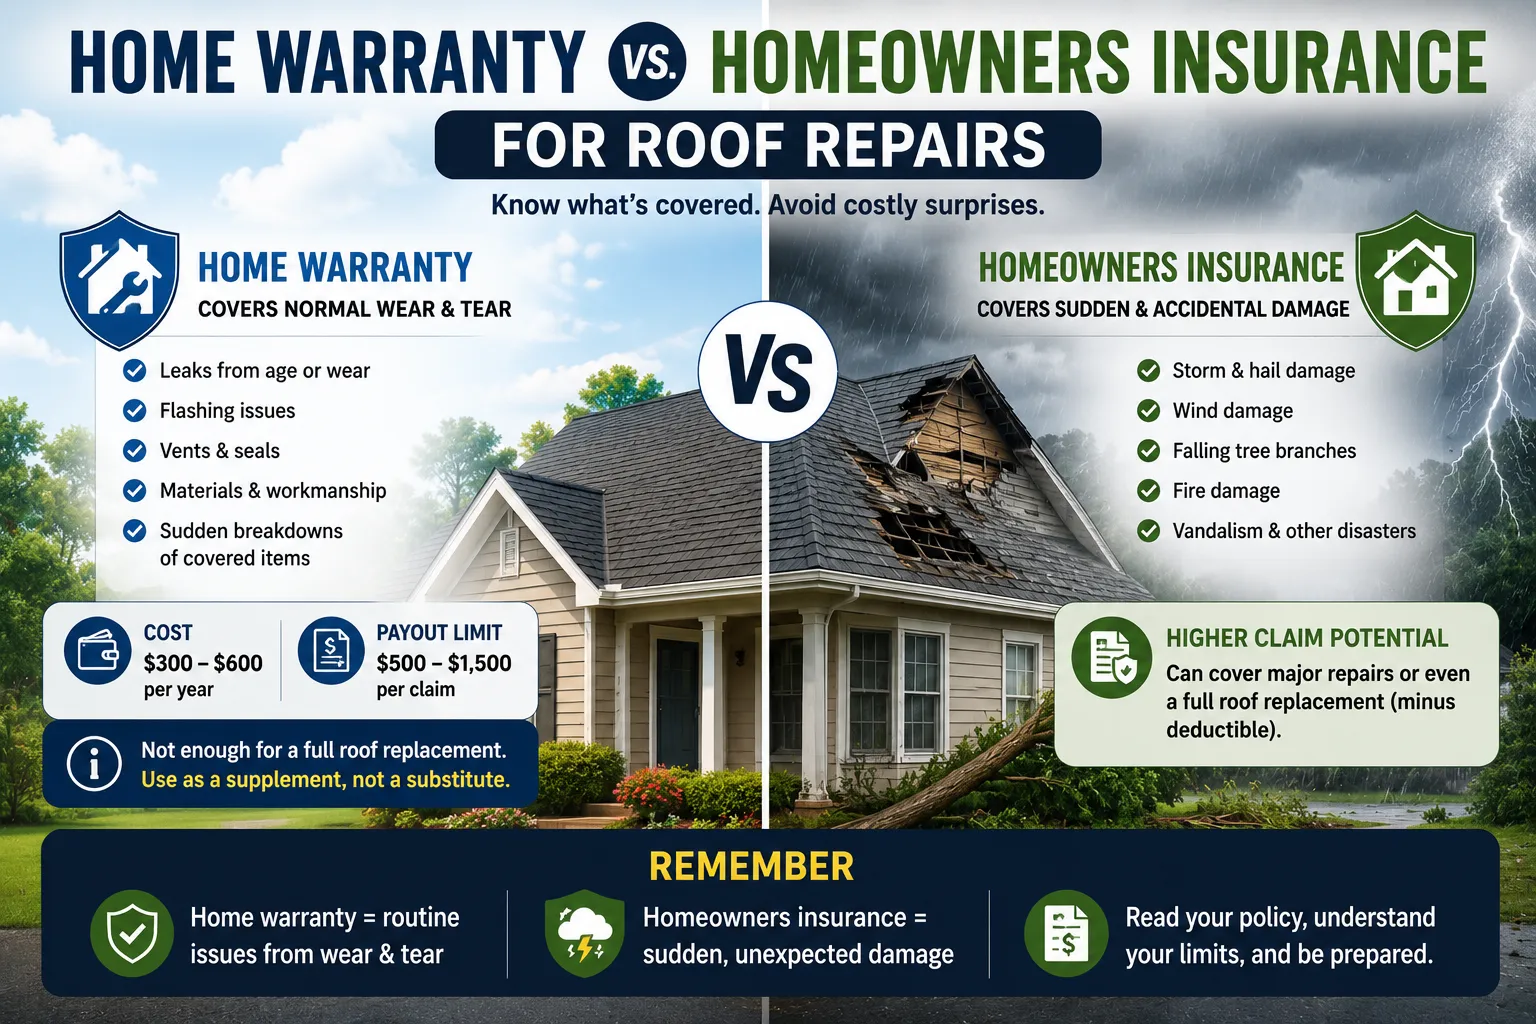
These cover different things, and mixing them up is a common (and costly) mistake. A home warranty covers leaks from normal wear, things like flashing and vents, while homeowners insurance covers sudden damage from storms, fire, or debris. Home warranty plans run $300 to $600 a year and typically cap payouts at $500 to $1,500 per claim, nowhere near enough for a full roof replacement. Treat it as a supplement to financing, not a substitute for it.
Conclusion
The right roof financing option isn’t the one with the lowest advertised rate. It’s the one that actually matches your equity, credit score, and timeline. If you have equity and no deadline, a home equity loan or HELOC wins on cost. Need it done now? A personal loan or contractor financing gets the job done in days. And if the upgrade is energy-related, PACE financing and energy-efficient mortgages open up a cheaper path that most guides never mention. Before any of that: file the insurance claim. It’s still the single step most likely to shrink what you actually need to borrow.